Sovereign Gold Bonds (SGB): Meaning, Benefits and How to Invest in India
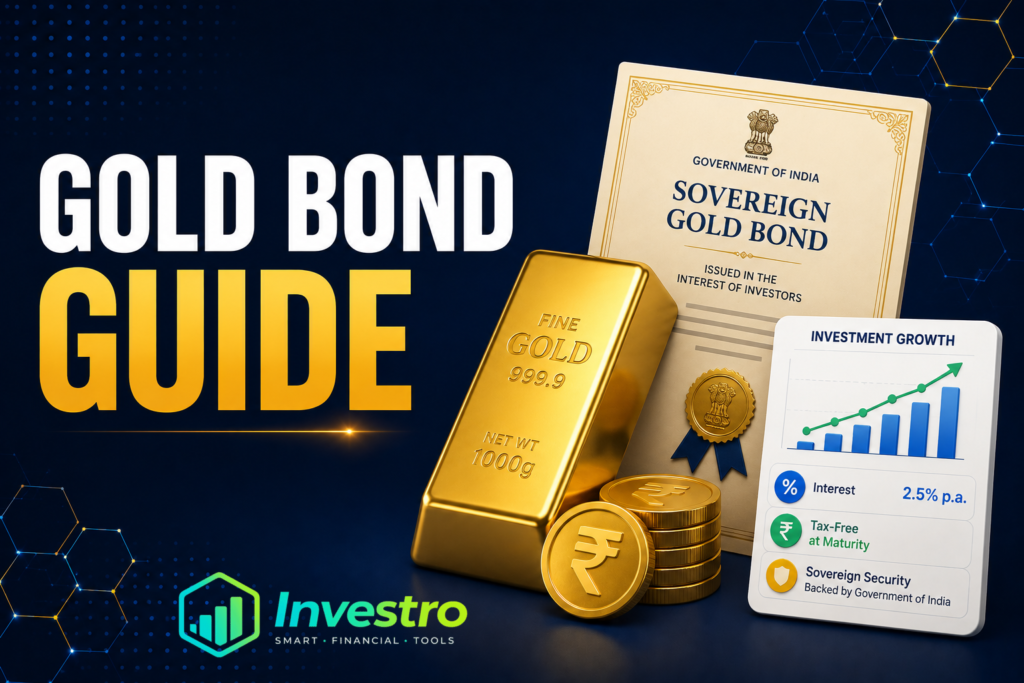
Sovereign Gold Bonds (SGBs) let you invest in gold without storage risk, plus earn 2.5% fixed annual interest and tax-free capital gains at maturity. Here is how SGBs work, their benefits, risks, and how to invest in India.
Gold has always been a favourite investment for Indians, but holding physical gold comes with storage risk and making charges. Sovereign Gold Bonds (SGBs) offer a smarter way to invest in gold — backed by the Government of India, with the added benefit of interest income. Here is everything you need to know before investing.
What Are Sovereign Gold Bonds?
Sovereign Gold Bonds are government securities issued by the Reserve Bank of India (RBI) on behalf of the Government of India. Each bond is denominated in grams of gold, meaning the value of your investment moves in line with the market price of gold, without you having to hold physical gold.
Since they are backed by the government, SGBs carry no default risk and are considered one of the safest ways to invest in gold in India.
Key Features of Sovereign Gold Bonds
Calculate While You Read
Free calculators related to this article — instant results, no signup.
Issuer
SGBs are issued by the RBI in tranches throughout the year, on behalf of the Government of India.
Tenure
The bonds have a tenure of 8 years, with an option to exit after the 5th year on interest payment dates.
Interest Rate
SGBs offer a fixed interest rate of 2.5% per annum on the initial investment amount, paid semi-annually, in addition to any gains from the rise in gold prices.
Minimum and Maximum Investment
The minimum investment is 1 gram of gold. Individuals can invest up to 4 kg per financial year, while trusts and similar entities can invest up to 20 kg.
How to Invest in Sovereign Gold Bonds
SGBs can be purchased through scheduled commercial banks, designated post offices, the Stock Holding Corporation of India (SHCIL), and recognised stock exchanges such as the NSE and BSE. They are issued in tranches with specific subscription windows announced by the RBI, and can also be bought and sold on stock exchanges after listing if you miss a fresh issue.
Benefits of Sovereign Gold Bonds
No Storage Risk
Since SGBs are held in electronic or paper form, there is no risk of theft or the need for locker charges, unlike physical gold.
Interest Income
Unlike physical gold or gold ETFs, SGBs pay a fixed 2.5% annual interest, giving you an additional income stream on top of potential price appreciation.
Capital Gains Tax Exemption
If SGBs are held until maturity (8 years), the capital gains are fully exempt from tax for individual investors. This is a significant advantage over physical gold and gold ETFs.
Usable as Loan Collateral
SGBs can be used as collateral to secure loans from banks and financial institutions, just like physical gold.
Sovereign Gold Bonds vs Physical Gold vs Gold ETF
Physical Gold
Physical gold involves making charges, purity concerns, and storage risk. It offers no interest income and attracts capital gains tax on sale.
Gold ETF
Gold ETFs track the price of gold and are easy to buy and sell on the stock exchange, but they do not pay any interest and are subject to capital gains tax, along with a small annual expense ratio.
Sovereign Gold Bonds
SGBs combine the price benefits of gold with a fixed interest income and tax-free capital gains at maturity, making them one of the most efficient ways to hold gold for the long term.
Risks and Limitations of Sovereign Gold Bonds
Lock-in Period
Although the tenure is 8 years, early exit is only allowed after the 5th year, which may not suit investors looking for short-term liquidity.
Gold Price Risk
The value of your investment still depends on gold prices. If gold prices fall, the value of your bond falls too, regardless of the fixed interest earned.
Limited Liquidity Before Maturity
While SGBs are listed on stock exchanges, trading volumes can be low, which may make it harder to sell at a fair price before maturity.
Who Should Invest in Sovereign Gold Bonds?
SGBs are ideal for long-term investors who want exposure to gold as a part of their portfolio without the hassle of physical storage. They particularly suit investors who can stay invested for 5 to 8 years and want to benefit from the tax-free capital gains at maturity.
Tips for Investing in Sovereign Gold Bonds
- Invest during official RBI subscription tranches to buy at the issue price, or purchase from the stock exchange if you missed a tranche.
- Consider staggering your investment across multiple tranches to average out your purchase price.
- Hold until maturity wherever possible to take full advantage of the tax-free capital gains benefit.
- Keep your gold allocation to a reasonable portion of your overall portfolio, typically 5-10%.
- Remember that the semi-annual interest is taxable as per your income tax slab, even though capital gains at maturity are exempt.
Conclusion
Sovereign Gold Bonds are one of the most efficient ways to invest in gold in India, combining price appreciation, guaranteed interest income, and tax-free capital gains at maturity. For long-term investors looking to add gold to their portfolio without the risks of physical storage, SGBs are worth serious consideration.
This article is for educational purposes only and should not be considered financial advice. Consult a qualified financial professional before making any investment decisions.
Explore Investro Tools
Frequently Asked Questions
Quick answers to common questions about this topic.
-
The capital gains on SGBs are fully tax-free if held until maturity (8 years). However, the semi-annual interest income is taxable as per your income tax slab.
-
Yes, you can exit after the 5th year on interest payment dates, or sell on the stock exchange anytime after listing, though liquidity may be limited.
-
The minimum investment is 1 gram of gold, making SGBs accessible to small investors.
-
Yes, SGBs are backed by the Government of India, so they carry no default risk, though the value still moves with gold prices.